如果你在盈利后总是把利润又亏回去,那么这个心理陷阱就值得警惕。
When the account has $8,000 in unrealized profit and you stare at the screen, a thought may appear: I've already made this much, so loosening up a little should be fine.
So the trade that you were used to taking with a 1-lot position became 3 lots.
The market then pulled back.
Facing a loss, you did not cut it in time as usual, because the account still had the profit earned earlier.
By the time you realize that risk has exceeded the plan, the original unrealized profit may have already given back a large portion, and may even be approaching the account's risk-control line.
If you have experienced a similar moment, the problem may not actually be your skill, or even your discipline—it may be that your brain is doing something you are not aware of.
The invisible ledger in your brain
Nobel Prize-winning economist Richard Thaler proposed in the 1980s a concept that later deeply influenced behavioral finance: mental accounting.
It describes a common phenomenon: people mentally divide money into different 'accounts' according to its source, use, and how it was obtained, and adopt different attitudes toward them.
The same 10,000 yuan—whether received as a year-end bonus or accumulated through long-term savings—may bring completely different psychological feelings when spent.
From an economic-value perspective, they are both 10,000 yuan; once they enter a person's decision-making system, however, they may be given different meanings.
Similar situations can also occur in trading accounts.
When an account starts to profit, the brain can easily separate the profitable portion from the initial capital psychologically.
Money already earned will gradually be regarded as a space that can bear more risk.
In their 1990 study, Thaler and Johnson summarized a similar phenomenon as the 'House Money Effect': after people have just made a gain, their acceptance of subsequent risk may increase, because the profit previously obtained psychologically reduces the pain of another loss.
When applied to trading, this change may manifest very concretely.
A previously fixed position size starts to increase, the stop-loss range widens, trading frequency rises, and some trades that would not be executed under normal circumstances also begin to enter the account.
The strategy has not changed, and the market may not have fundamentally changed either; what changes is the trader's psychological definition of the account's funds.
After making a profit, risk standards may also quietly change
A very typical manifestation of mental accounting in trading is that traders adopt different risk standards for 'principal' and 'profit'.
When an account first starts, position size, stop-loss, and per-trade risk usually have a clear plan; but once the account has accumulated some profit, the original boundaries tend to slowly loosen.
Position sizes that would not have been accepted before start to feel 'worth a try'; and a stop-loss level that should originally have been triggered may be waited on longer because there is still profit.
That is exactly where the problem lies.
From the perspective of trading results, both the principal and profit in the account will ultimately be reflected on the same equity curve.
Once profit enters the account, it likewise needs to be incorporated into risk management, rather than becoming an extra risk budget.
The dynamic drawdown rules of EagleTrader Max make this very intuitive.
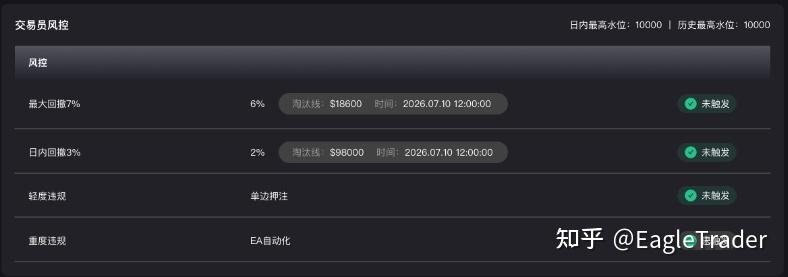
Max sets a 7% maximum drawdown and a 3% maximum intraday drawdown, and both risk-control lines move with the account's high-water mark.
Among them, the maximum drawdown risk-control line is calculated as 'historical high-water mark - initial account size × 7%'.
For example, for a $100,000 account, when the historical high net value reaches $109,000, the maximum drawdown risk-control line will move up in sync to $102,000.
This means that after the account creates new profit, the risk boundary will also change accordingly.
The $9,000 earned previously will not all become space that can bear risk again because of this.
The dynamic 3% intraday drawdown follows similar logic.
After the account's net value reaches a new high during the day, the intraday risk-control line will also adjust accordingly.
Therefore, having already made a profit in the morning does not mean that you can correspondingly increase position size or raise trading frequency in the afternoon.
The two rules correspond to different time scales: 7% focuses on the entire account cycle, while 3% focuses on a single trading day, but they both point to the same question—after the account makes a profit, can the trader still maintain the original risk standards?
This is also where mental accounting is most likely to affect trading decisions.
Many times, the strategy has not changed, and the market has not required the trader to increase risk; it is simply because the account has already made money that the person's acceptance of the same loss has changed.
Rules will not eliminate this psychological tendency, but they can draw a clear boundary for risk.
For traders who have already developed a mature trading system, what truly needs to be maintained is that whether the account is in profit or drawdown, position size, stop-loss, and risk budget are still built on the same logic.
Return to the $8,000 unrealized profit at the beginning of the article.
If this portion of profit had not appeared, you might not have suddenly increased from 1 lot to 3 lots, nor would you have been willing to let a trade that should have been stopped out continue running.
So what changes your decisions is not necessarily the market; it could also be the way you manage your funds.
Ready to take on EagleTrader Max?
No upfront evaluation stage. Trade immediately once funded, with up to 90% profit split.