当过去的交易经历开始影响下一笔交易时,真正的风控应该怎么做?
After a trader was stopped out of a heavy position in 2023, for the next two years, whenever he encountered a similar opportunity, he would subconsciously shrink his position size.
It was not the strategy requiring him to do so, and there was no data supporting the judgment that "this time it will also lose."
But his hand just did not dare to pull the trigger.
Another trader caught a big market move in 2022.
Afterward, whenever the market showed a similar signal, he was more aggressive than usual — larger position, earlier entry, wider stop-loss.
On the surface, one is conservative and the other aggressive, but they are doing the same thing: letting a certain past experience place orders for their present selves.
And they may not realize it.
Memory secretly rewrites your risk preference
In 2024, NBER published a study based on real trading data from 17,000 Chinese retail investors.
Researchers found that investors do not make decisions based on all historical experience, but form expectations based on "remembered experiences."
More critically, these remembered experiences even have greater explanatory power for expectations than actual experiences themselves.
On days when the market rises, investors are more likely to recall fragments of their past profits, and thus become more optimistic about the future; on days when the market falls, loss memories are retrieved, and expectations turn bearish.
Laboratory studies have found a similar direction: when participants first recall profitable trades before investing, their subsequent bets are more aggressive; while the inhibitory effect brought by recalling loss fragments is far less symmetrical than imagined.
This shows that the brain is not "objectively referring to past experience."
It is prompted by the current market and emotions, selectively retrieves a certain memory, and then uses that memory to redefine your sense of risk.
You think you are making judgments, but in fact the current market has already chosen the past for you to recall.
It will disguise itself as two judgments that look very "reasonable"
Memory bias does not appear in the form of "I am being influenced by memory."
It puts on the coat of analysis.
The first: "there is an opportunity this time" after making a profit.
You once made a profit with a heavy position in a certain type of market, and that experience was marked by the brain as a success template.
Later, when encountering similar signals, the brain automatically retrieves this memory, making you feel "there is an opportunity this time too."
The position size expands without you realizing it, and the stop-loss widens without you realizing it. You think you are doing a review, but you are actually just replaying a recording.
At such times, the mistake people are most likely to make is not failing to make money, but returning the profit just pocketed together with the principal — because when things are going well, people sincerely believe "the feel is here," and the profit on the books is never yours before you exit.
The second: "wait a little longer" after a loss.
You once had an experience where you did not exit a floating loss, and the market eventually came back.
This memory was marked by the brain as "patience works."
Afterward, every time there is a floating loss, the same voice pops up: "Hold on a bit longer; didn't it come back last time?" Support levels, resistance levels, fundamentals—you can find reasons for all of them, but what really keeps you from acting is that old experience.
And one stubborn hold can often wipe out the previous ten small profits.
Because when you are in floating loss, you can always find a reason not to cut, but the market will not give you another chance just because you "held on and it came back last time."
Why self-monitoring fails
The problem is that in both states you sincerely believe you are right.
When things are going well, you truly believe "this time is different"; when losing, you truly believe "hold on a little longer and it will come back."
Asking the person who is influenced by memory to judge whether he is influenced by memory — this itself is unreliable.
So what you need is not "more effort to be aware," but a risk-control line that you set in advance, execute when reached, and leave you no room to bargain.
What EagleTrader Max does is put risk control upfront as an account-level hard constraint.
It does not care what you are thinking at this moment; it only recognizes pre-set numbers.
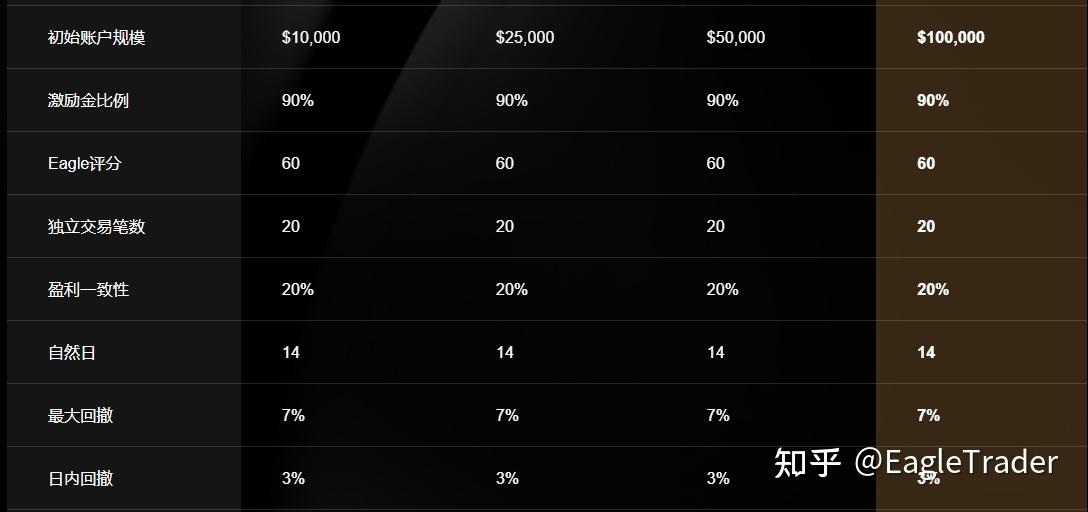
For "increasing position size after profit," it uses a maximum drawdown line based on the historical high-water mark —7%, which only rises and never falls.
If the account goes from 100,000 to 109,000, the drawdown line moves up accordingly from 93,000 to 101,300.
The newly earned 9,000 is no longer capital for you to lose.
You did well, and the line follows you; if you want to enlarge risk because of successful experiences in your memory, this line will not give you one millimeter more room.
For “holding on stubbornly after a loss,” it uses an intraday drawdown line based on the day's highest watermark — 3%, reset every trading day.
If the morning goes smoothly, the afternoon line will not loosen just because “you've already made money today.”
It does not care which memory you are replaying in your head; it recognizes only one number: how much room you have left from today's highest point.
When you reach the line, you leave — the option to “wait a bit longer” does not exist at the system level.
It also looks one layer further: it checks whether your profits are distributed across many repeatable trades or concentrated in a few heavy bets. This is the role of “profit consistency” in the Max profit-sharing conditions.
This psychology is essentially that the brain amplifies those impressive experiences and uses them to quickly judge the risk in front of it.
To change it, the key is not to force yourself to forget the past, but to bring every trade back to the strategy, probability, and risk rules themselves.
And a risk-control mechanism like EagleTrader Max can fix part of the risk boundary in advance, reducing the interference of emotions and past experiences with execution.
The past can become experience, but it should not become the decider of the next trade.
Ready to take on EagleTrader Max?
No upfront evaluation stage. Trade immediately once funded, with up to 90% profit split.